|
The time to file income tax returns is around the corner. It is important for you to understand the basic tax liability for payment of income tax for the year 2005-06 . Any shortfall in tax payment for the last year (i.e. till March 31, 2006) may be paid now, along with interest.
The Finance Act 2005 had specified the rates of income tax for the assessment year 2005-06 and the rates of income tax on the basis of which tax has to be deducted and advance tax has to be paid during the financial year 2005-06.
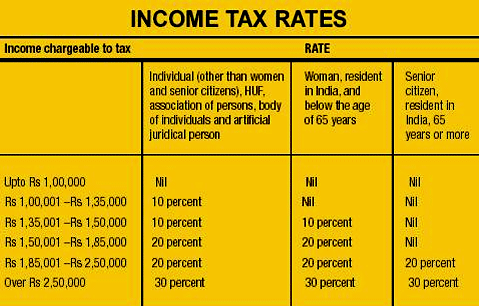
The rates for deduction of income tax at source from salaries during the financial year 2005-06 and also for computation of advance tax payable during that year in the case of all categories of tax payers have been specified in the Act. These rates are also applicable for charging income tax during the financial year 2005-06 on current incomes in cases where accelerated assessments have to be made, e.g., assessment of persons leaving India for good during that financial year, assessment of persons who are likely to transfer property to avoid tax etc (see table).
The tax payable would be enhanced by a surcharge at the rate of ten percent of the tax payable (after allowing rebate under Chapter VIII-A ) in cases of individuals, Hindu undivided families, association of persons, and body of individuals with a total income exceeding Rs 10 lakhs. No surcharge would be payable by persons having incomes of Rs 10 lakhs or below.
Marginal relief would be provided to ensure that the additional amount of income tax payable, including surcharge, on the excess of income over Rs 10 lakhs is limited to the amount by which the income is more than Rs 10 lakhs. For example , the amount of tax and surcharge on a total income of Rs 10,20,000 calculated at the rates specified would have been Rs 2,56,000 and Rs 25,600 totalling to Rs 2,81,600.
The additional tax liability, as per this computation, incurred as compared to a person having a total income of Rs 10,00,000 is Rs 31,600. However, additional income as compared to a person having a total income of Rs 10,00,000 now comes to only Rs 20,000. Therefore, a marginal relief is given to the extent of Rs 11,600 in this case thereby providing that the additional tax liability cannot be more than the additional income. The total tax liability in this case will, therefore, be Rs 2,76,000.
Education cess
An additional surcharge called education cess is to be levied at the rate of two percent on the amount of tax computed, inclusive of surcharge , if any. For instance, if the income tax computed is Rs 2,00,000 and the surcharge is Rs 20,000, then the education cess of two percent is to be computed on Rs 2,20,000 which works out to be Rs 4,400. No marginal relief will, however, be available in respect of the education cess.
|






